Co-Marketing Agreements
Part of Co-marketing budget management
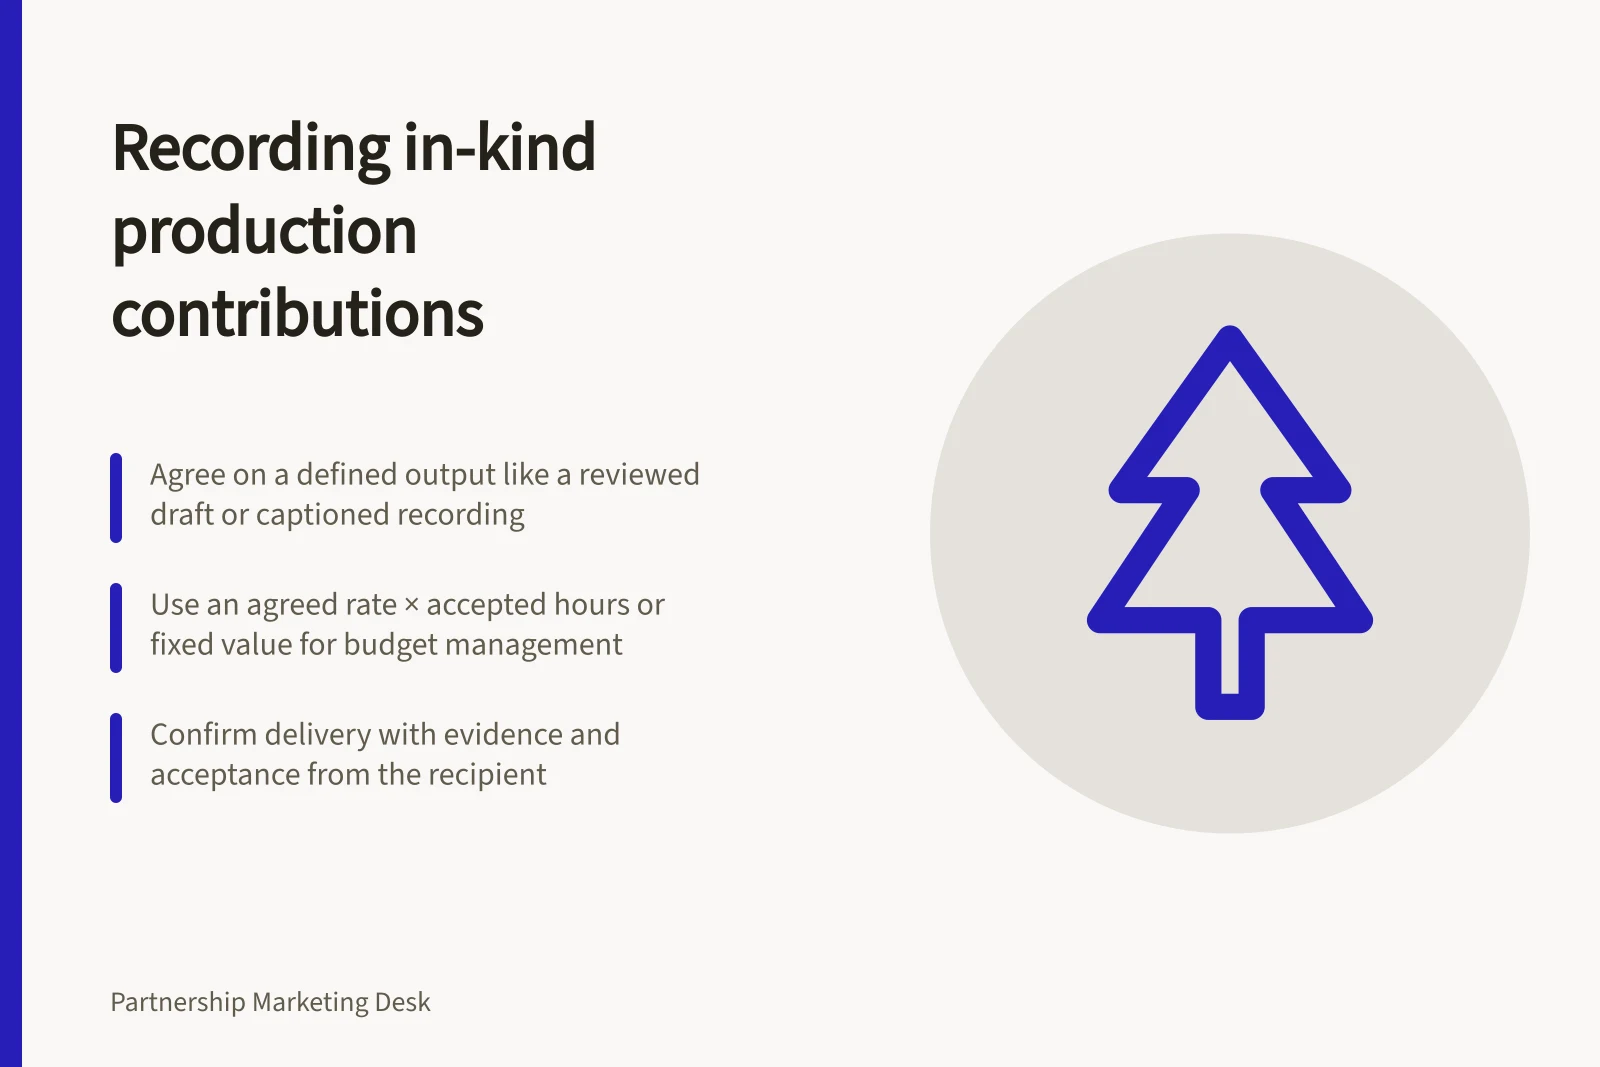
Recording in-kind production contributions
Document a partner's in-kind campaign work with a defined output, agreed value, delivery evidence and clear separation from cash spending.
Record an in-kind contribution as defined work or an asset supplied for the joint campaign. Note who provides it, what delivery means, the evidence of delivery and any value the partners agree to use for budget management. Keep that value separate from supplier invoices and cash payments.
Key facts about in-kind contributions in Australia
- Source guidance
- Business.gov.au & VicGov grants guidelines
- GST treatment
- Generally not subject to GST if no consideration is exchanged
- ATO position
- In-kind contributions must be valued fairly and consistently
- Common examples
- Design work, editing, venue use, software licences
- Documentation need
- Evidence of delivery and acceptance required
Describe what will be delivered
"Help with production" is too broad to check. Name the output, such as a reviewed draft, designed file, captioned recording or specified use of a facility. Set its due point, included revisions or uses, and acceptance condition. Check that any existing licence or third-party work permits the intended campaign use before counting the asset as available.
| Field | What to record |
|---|---|
| Output | Defined work or asset and its campaign purpose |
| Provider and recipient | Who supplies it and who will use or accept it |
| Limit | Maximum hours, versions or uses included |
| Value basis | Agreed rate and accepted hours, fixed value, or no monetary value |
| Evidence | Work record, delivered file or acceptance note |
| Budget treatment | Agreed cash-share adjustment or total-effort view only |
If the partners intend the contribution to reduce a cash obligation, agree the method and cap before work starts. A value recorded for context alone does not change a reimbursement.
Choose a reproducible management value
For time-based work, an agreed rate multiplied by accepted hours is straightforward to calculate. Define the task and maximum so extra hours do not automatically create extra credit. A fixed value for a finished output avoids counting time but needs a clear acceptance condition. If a defensible amount adds little to the decision, describe the contribution without pricing it.
For example, if a partner promises up to an agreed number of specialist editing hours at an agreed management rate, calculate the value of accepted hours by multiplying them by that rate. Apply the partners' stated rule for partial delivery. This illustrative calculation is for campaign budget management only; it does not represent cash paid to a supplier or determine tax treatment.
Count each input once. An agency design invoice is a supplier cost; a partner's payment of that invoice is not also in-kind design work. Keep reimbursement between partners separate from the value of employee work.
Confirm actual delivery
At the agreed review point, compare the promise with the received output. Retain the relevant file, work record or approval and note partial delivery. Ask the receiving partner to confirm acceptance; hours recorded alone do not show that the agreed output was supplied.
Where useful, show outside cash costs, cash paid by each partner and accepted in-kind contributions as separate views. A combined total-effort figure may help planning, but it is not the cash needed to pay suppliers. Each business should have its finance adviser assess any accounting or GST consequences of the actual arrangement and documents.